Flat purchase fell through because of ALTA: what about property tax
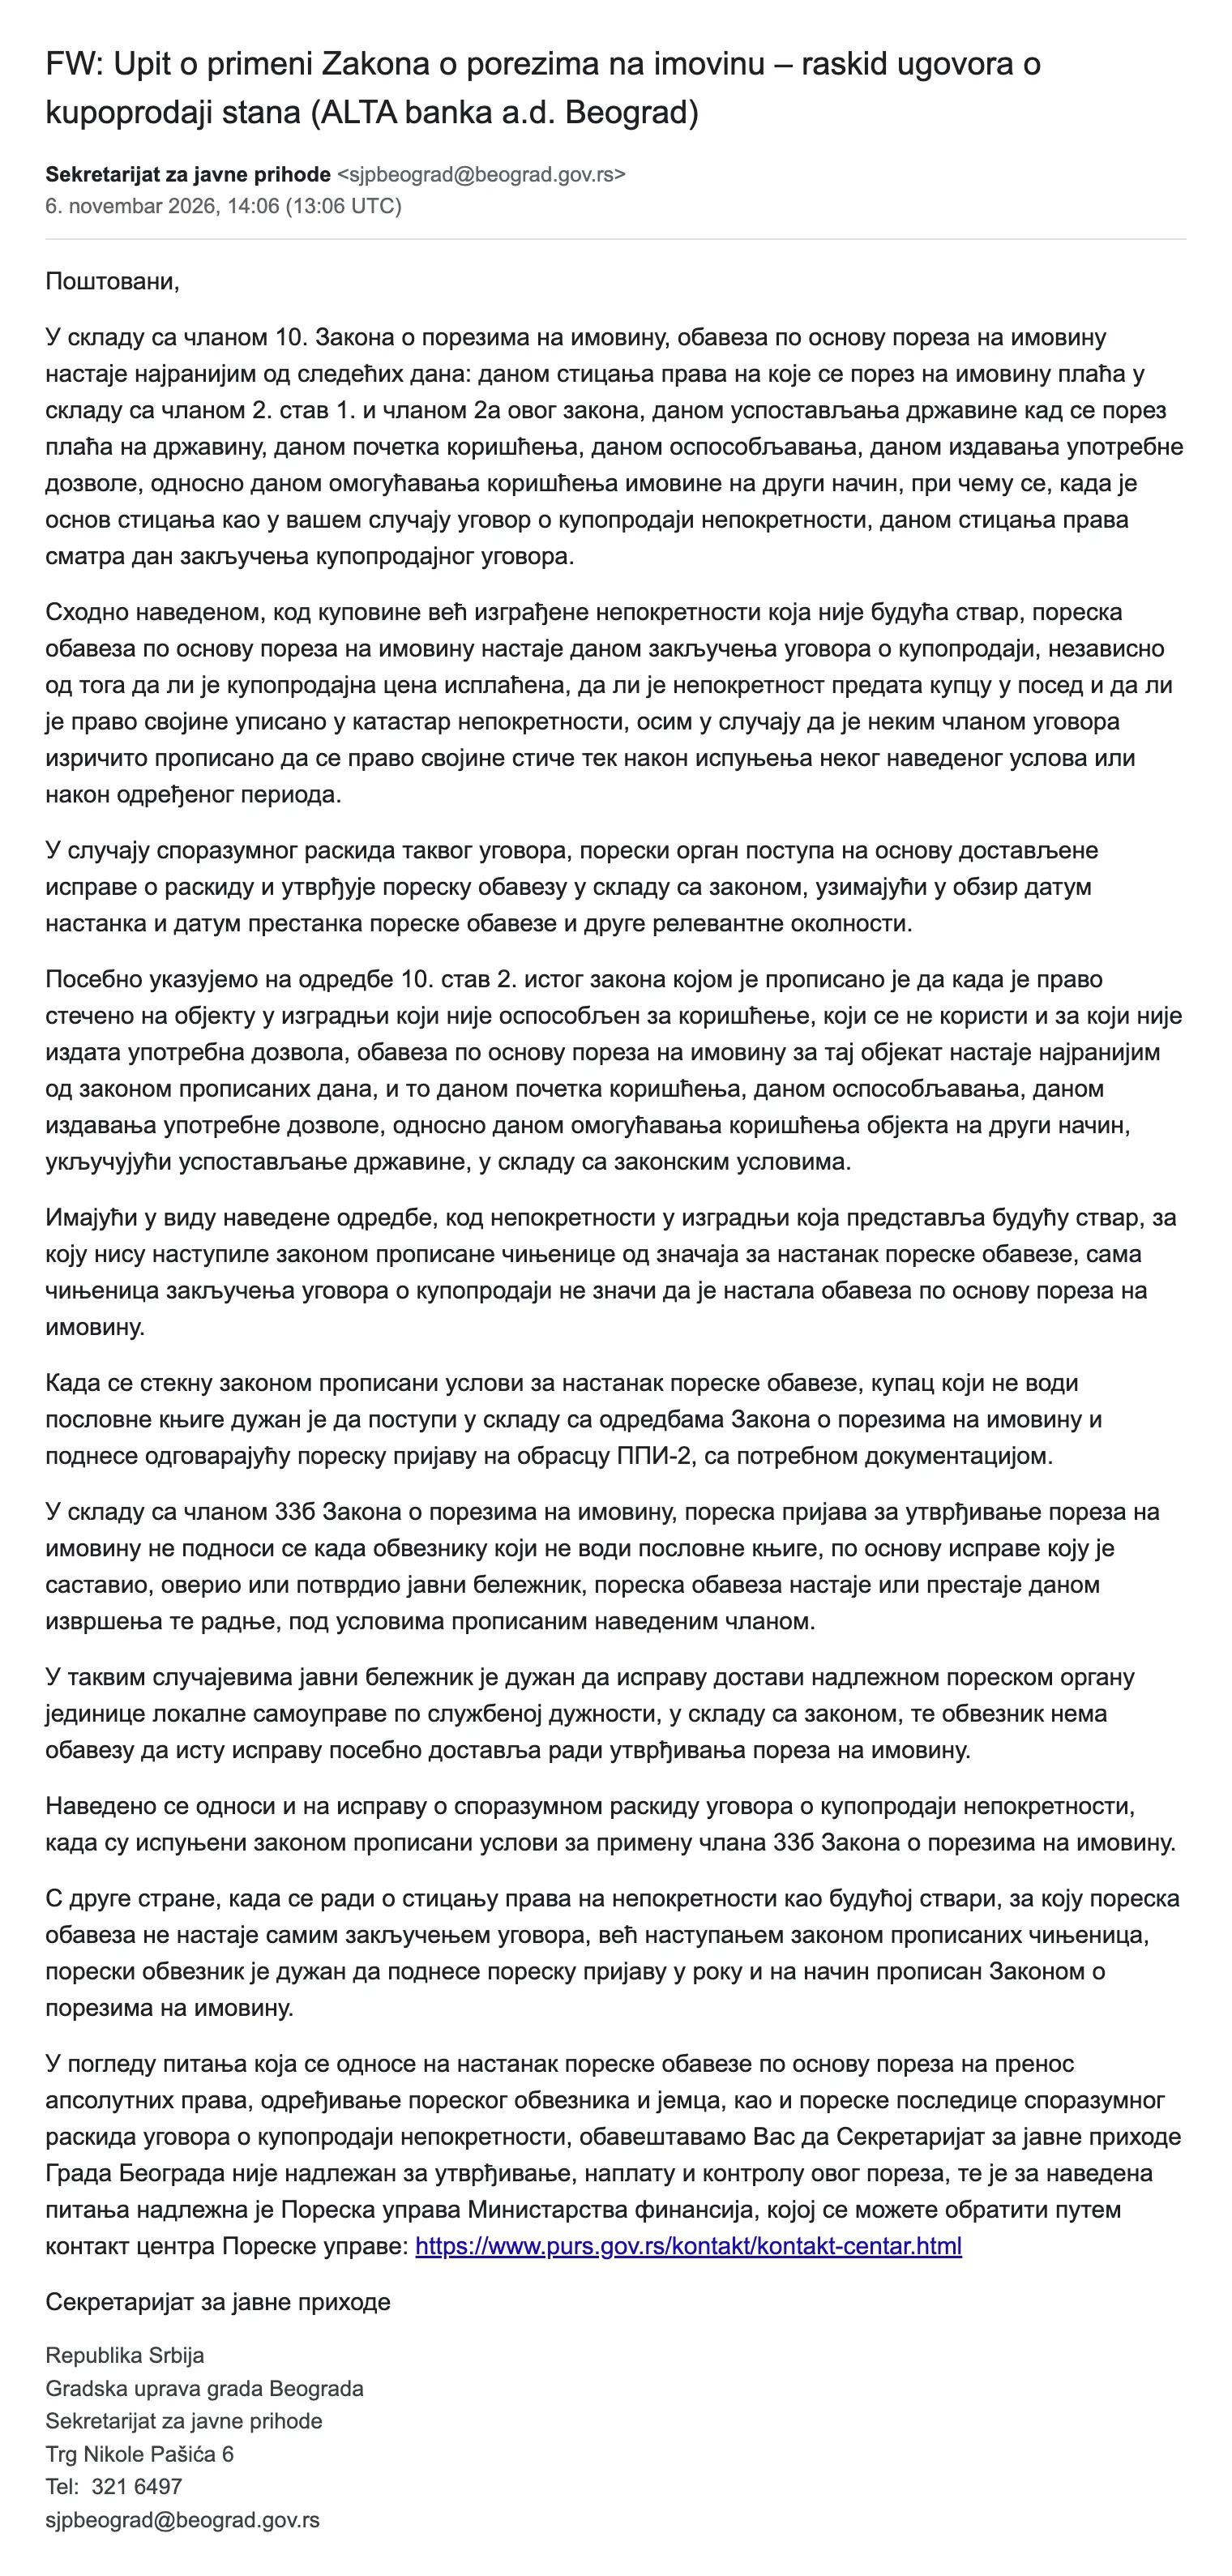
Many depositors signed flat purchase contracts before a notary on 29–30 October 2026. They were to pay from an ALTA account, but the bank’s licence was revoked on 30.10 and the payment did not go through. Now the contracts are being cancelled. A depositor asked Belgrade’s city tax authority what happens with property tax (porez na imovinu) in this case. A written answer arrived on 06.11.2026. Below is what it says in plain words, with verbatim quotes.
In short
Section titled “In short”- Completed flat. The property tax liability arises on the date the contract is signed — even if you have not paid, the flat has not been handed over and nothing has been entered in the cadastre. The exception is a contract that explicitly says ownership passes only once a condition is met (for example, payment).
- Cancellation by mutual agreement. The tax authority assesses the tax based on the cancellation document, taking into account the day the liability arose and the day it ended.
- Cancellation done before a notary — the notary sends the document to the tax authority, provided the conditions of Art. 33b of the law are met. You do not need to file a PPI-2 return because of the cancellation.
- Flat in a building under construction (legally, “future property”). Signing the contract alone does not create a property tax liability.
- Transfer tax (porez na prenos apsolutnih prava) is not handled by the city but by the Tax Administration of Serbia. Ask through its contact centre.
Completed flat: tax from the contract date
Section titled “Completed flat: tax from the contract date”Under Art. 10 of the Law on Property Taxes the liability arises on the earliest of several dates, including the day the right is acquired. The Secretariat writes that for a purchase under a contract, the day the right is acquired is the day the contract is concluded:
«…код куповине већ изграђене непокретности која није будућа ствар, пореска обавеза по основу пореза на имовину настаје даном закључења уговора о купопродаји, независно од тога да ли је купопродајна цена исплаћена, да ли је непокретност предата купцу у посед и да ли је право својине уписано у катастар непокретности, осим у случају да је неким чланом уговора изричито прописано да се право својине стиче тек након испуњења неког наведеног услова или након одређеног периода.»
What to check: whether your contract has a clause that ownership passes only after payment or another condition. If it does, then according to the answer the tax does not arise on the contract date.
Cancellation by mutual agreement
Section titled “Cancellation by mutual agreement”«У случају споразумног раскида таквог уговора, порески орган поступа на основу достављене исправе о раскиду и утврђује пореску обавезу у складу са законом, узимајући у обзир датум настанка и датум престанка пореске обавезе и друге релевантне околности.»
So the tax authority looks at two dates: the contract and the cancellation. The answer does not say how much will be charged for this period, or whether anything will be charged at all.
Cancellation at a notary: no return to file
Section titled “Cancellation at a notary: no return to file”If the cancellation document was drawn up, certified or confirmed by a notary (javni beležnik), no tax return is filed — this follows from Art. 33b of the law. The Secretariat:
«У таквим случајевима јавни бележник је дужан да исправу достави надлежном пореском органу јединице локалне самоуправе по службеној дужности, у складу са законом, те обвезник нема обавезу да исту исправу посебно доставља ради утврђивања пореза на имовину.»
«Наведено се односи и на исправу о споразумном раскиду уговора о купопродаји непокретности, када су испуњени законом прописани услови за примену члана 33б Закона о порезима на имовину.»
The law itself (Art. 33b para. 2) gives the notary 24 hours to pass the document to the tax authority through the electronic counter (e-šalter).
Flat in a building under construction
Section titled “Flat in a building under construction”For a building under construction that is not fit for use, is not used and has no occupancy permit (upotrebna dozvola), the liability arises on the earliest of these dates: the start of use, the day it becomes fit for use, the day the permit is issued or the day possession is taken (Art. 10 para. 2). The Secretariat:
«…код непокретности у изградњи која представља будућу ствар, за коју нису наступиле законом прописане чињенице од значаја за настанак пореске обавезе, сама чињеница закључења уговора о купопродаји не значи да је настала обавеза по основу пореза на имовину.»
When those conditions are met, a buyer who is a private individual and does not keep business accounts files the PPI-2 return themselves.
Transfer tax — ask the Tax Administration
Section titled “Transfer tax — ask the Tax Administration”The city Secretariat does not answer who pays the transfer tax under the contract and what happens to it on cancellation: this tax is handled by the national Tax Administration (Poreska uprava, Ministry of Finance). The Secretariat:
«…Секретаријат за јавне приходе Града Београда није надлежан за утврђивање, наплату и контролу овог пореза, те је за наведена питања надлежна је Пореска управа Министарства финансија…»
You can ask through the Tax Administration contact centre.
The Secretariat’s full answer
Section titled “The Secretariat’s full answer”